Checkbook - Account Tracker
TinyWork Apps
- 3.6
- 4.29K Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
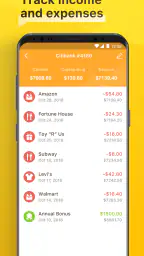
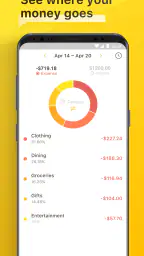
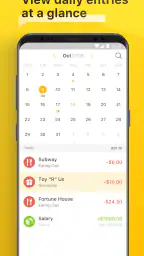
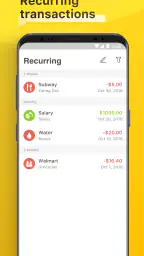
Checkbook - Account Tracker Pros and Cons
Pros
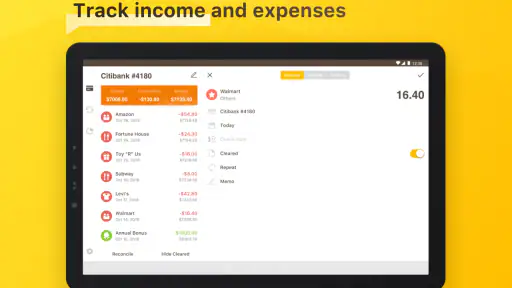
- Simple interface makes recording income and expenses quick.
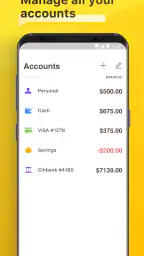
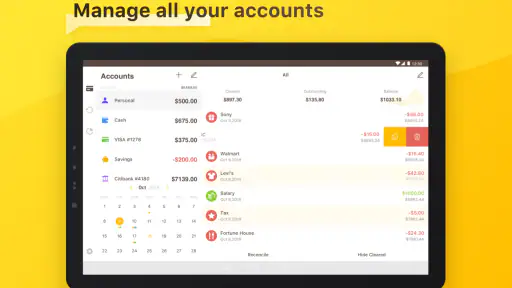
- Supports multiple accounts for better financial organization.
- Recurring transactions reduce repetitive manual entries.
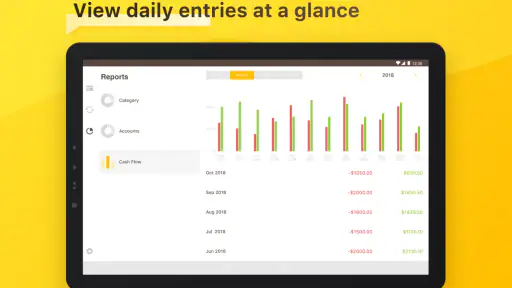
- Useful reports help identify spending patterns over time.
- Works well for users who prefer manual budget control.
Cons
- Manual entry can become tedious with frequent daily transactions.
- Some advanced features may require a paid upgrade.
- Limited automation compared with bank-linked finance apps.
- Data accuracy depends on consistently categorizing transactions.
- May feel basic for users needing detailed investment tracking.
 Analysis by All-app
If you still balance your spending by checking a paper register, Checkbook - Account Tracker takes a familiar idea and puts it on your phone. I found it most useful as a simple running record for money going in and out, rather than as a full banking dashboard. That distinction matters: this is a finance app for recording transactions, not a replacement for your bank’s secure account view.
The first impression is deliberately practical. TinyWork Apps has kept the focus on the checkbook-register method, which makes the app approachable for someone who wants to know what their balance should be after a few purchases, bills, or deposits. It is free to install, rated for Everyone, and the current version is 2.1.2. Optional in-app purchases range from under a dollar to around twenty dollars per item, so I would look at the available options before paying for anything.
What to expect from this account tracker
The best way to understand this app is to imagine a paper checkbook register with the convenience of a phone. You enter a transaction, keep an eye on the resulting balance, and use that record to avoid relying on memory. That is a narrower job than automatic budgeting apps perform, but it can also be less distracting.
I would recommend it to someone who wants a lightweight manual ledger for a checking account, cash spending, or a small household account. It can also suit people who do not want to connect financial accounts to a third-party service. The trade-off is that you must enter transactions yourself. If you expect automatic synchronization, categorized spending charts, bill reminders, or a complete financial overview, this is probably not the right first choice.
Its long presence on the platform gives it a useful level of familiarity. The app was released in mid-2015, and it has passed one hundred thousand installs, with an average rating of 3.6 from roughly nine thousand ratings and more than four thousand written reviews. I would read that as a sign that the basic idea works for a defined audience, while the middling score also suggests that simplicity will not satisfy everyone.
Before installing, I would make one decision: choose the account you want to track first. Trying to recreate every account, card, and savings goal immediately can turn a straightforward register into a chore. Starting with the account where you most often lose track of pending purchases gives the app a much better chance of becoming part of your routine.
Setting up a clean starting point
On first use, I would begin with the current balance shown by the real account, not with an old statement balance that still needs several corrections. The purpose of this first entry is to create a reliable starting line. If you begin with the wrong amount, every later calculation may look neat while remaining wrong.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Next, decide how much detail you can maintain consistently. A useful minimum is the date, amount, and a short description that will still make sense later. For example, “market” is more helpful than “purchase,” while “electric bill” is more useful than a vague note such as “online.” The app is only as valuable as the record you keep inside it, so a small amount of consistent detail beats elaborate entries that you soon abandon.
I also suggest entering transactions as soon as possible, especially card purchases that have not appeared in your bank balance yet. This is where a manual register has a quiet advantage over simply opening a banking app: you can record your expected spending immediately and see the balance you should have after it clears. That can prevent the common mistake of treating money that is already committed as available.
For a shared household, agree on one rule before using the tracker: either one person records everything, or both people add transactions promptly. A register becomes confusing when one person records a bill and the other assumes the balance already includes it. The app does not remove that household coordination problem, but its straightforward format makes a shared routine easier to explain.
Android compatibility is also worth checking before you commit to the workflow. The listed minimum is Android 7.0, so older devices may not be suitable. On a supported phone, I would still spend a few minutes learning where entries are created and how the balance is displayed before relying on it for a busy account.
The first meaningful success: record one real purchase
The quickest way to decide whether this app fits you is not to explore every screen. Record one transaction that you made today, then compare the displayed result with the amount you believe remains in the account. This small test tells you whether the register’s interaction feels natural enough for daily use.
For a realistic example, imagine buying lunch after work while a utility payment is scheduled for the next morning. I would first record the lunch purchase, then add the upcoming payment if it has already been authorized or is certain to leave the account. The resulting figure is more useful than the bank’s current balance because it reflects money that is already spoken for.
That workflow is one of the app’s strongest practical uses. It turns the register into a short-term decision tool: before buying something optional, I can check the balance after known commitments rather than guessing from the number shown by the bank. It is especially helpful during the few days before payday, when several pending expenses can make an account look healthier than it really is.
Another useful habit is a quick reconciliation session. Compare the app’s entries with recent bank activity, mark down anything missing, and correct mistakes while they are still easy to identify. I would do this at a regular moment, such as after reviewing a statement or when a deposit arrives. The important insight is that reconciliation is not a sign the app failed; it is the maintenance that keeps a manual tracker trustworthy.
Do not use the first successful result as proof that every future balance will be correct automatically. A forgotten cash withdrawal, a duplicated entry, or a payment that changes amount can throw off the register. The app helps you maintain a model of your money, but you remain responsible for checking that model against reality.
Where new users can get confused
The biggest source of confusion is usually the difference between a transaction being recorded and a transaction being cleared by the bank. A manual register lets you account for spending before it appears in the official balance. That is useful, but only if you understand which figure represents your current bank balance and which figure represents your planned position after pending items.
I would avoid entering the same payment twice simply because it first appears as pending and later appears as completed. Instead, treat the register as your own record and update the original entry when appropriate. The exact routine depends on how you manage your account, but the principle is simple: one real-world transaction should have one clear place in your ledger.
Transfers can also make a register look wrong if they are treated as ordinary income or spending. When money moves between accounts, the total picture has not necessarily changed; it has changed location. If you decide to track more than one account, label transfers carefully and check both sides so that the same movement does not accidentally inflate or reduce your overall view.
Cash is another area where discipline matters. A cash withdrawal is not the same as the final purchases made with that cash. If you record the withdrawal and then record every cash purchase as though the money left the bank again, the account will be understated. I would either track the withdrawal as the account transaction or maintain a separate cash record, but not mix the two casually.
Descriptions deserve more attention than they usually receive. A short, repeatable naming style makes later checking much faster. I prefer descriptions that identify the purpose first, such as “rent,” “fuel,” or “school supplies,” rather than relying on merchant names that may be unfamiliar when they appear on a statement. This is a small workflow choice, but it is one of the practical advantages of entering your own data.
The app’s average rating of 3.6 is a useful reminder to keep expectations realistic. A register can feel excellent when you want control and frustrating when you want automation. That difference is not solved by entering more data; it is a question of whether manual tracking matches the way you handle money.
How it compares with banking and budgeting alternatives
Your bank’s app remains the better source for official balances, cleared transactions, transfers, and account security. I would never use this tracker as a substitute for checking the bank when a payment is important or a balance seems unusual. The bank knows what actually processed; this app helps you plan around what you have recorded.
Compared with a spreadsheet, the app is likely to feel more direct for quick phone entries. A spreadsheet offers greater flexibility for formulas, custom categories, long-term reports, and multiple financial models, but that flexibility can make everyday recording feel like administration. If your main need is a running register rather than analysis, a dedicated checkbook-style tool is easier to approach.
Compared with automatic budgeting services, the trade-off is even clearer. Those services can reduce manual work and show broader spending patterns, while a register gives you more deliberate control over what is recorded. I would choose this app for privacy-minded manual tracking or for a single account that needs close attention. I would choose an automatic service when I need several accounts combined, recurring analysis, or spending categories generated for me.
It also sits between a notes app and a full finance suite. A notes app may be faster for a rough list, but it will not give the same focused register experience. A larger finance suite may provide more tools than you need and demand more setup. Checkbook - Account Tracker makes sense when the middle ground is the goal: more structured than notes, less ambitious than financial planning software.
Who should use it, and who should skip it
I think this app is a good match for first-time budgeters who want one dependable habit: record spending and know the expected balance. It can also help students, people managing a tight monthly account, and anyone who used to keep a paper register but wants that process on a phone. The method is understandable without requiring a strong interest in financial terminology.
It may be useful for a small personal account where every transaction matters and the number of entries stays manageable. It can also work as a temporary training tool. Someone learning to distinguish available money from committed money may gain more from manually recording purchases for a month than from looking at a polished chart that hides the underlying decisions.
I would skip it if you know you will not enter transactions consistently. Manual tracking is not forgiving: one missed purchase can make the entire balance misleading. I would also look elsewhere if you need investment tracking, detailed debt planning, automatic imports, or a complete household budget with reports. Those needs call for a broader financial app or the official tools provided by your bank.
People who share finances should test the routine before making it the household’s only record. If both partners can update it promptly and agree on how to handle pending payments, it may be useful. If one person expects automatic visibility into the other person’s activity, the manual approach will create more friction than clarity.
Practical habits that make the register reliable
My strongest recommendation is to treat every entry as a small promise to your future self. Add enough information to recognize it later, and do it close to the moment the transaction happens. Waiting until the end of the week may seem efficient, but memory tends to blur similar purchases and turns reconciliation into detective work.
Keep the first account simple. Once you can maintain it without hesitation, add another account only if doing so answers a real question. For example, a separate savings record may be worthwhile if you regularly move money there and need to know what remains available for daily spending. Adding accounts merely because the app allows a broader setup can create unnecessary maintenance.
Use the tracker before making a decision, not only after money has left. Checking the expected balance before a discretionary purchase is more valuable than discovering a problem later. This turns the app from a historical list into a small planning checkpoint, which is where I found the manual approach most rewarding.
Finally, keep the bank as the final authority. If the two records disagree, investigate the difference instead of assuming the app is right. Look for a forgotten entry, a duplicate, a changed payment amount, or a transfer recorded on only one side. That habit protects you from the most serious weakness of every manual ledger: confidence in a number that has not been checked.
My recommendation after using it
Checkbook - Account Tracker is a focused finance app that succeeds when you want a digital checkbook register and accept the responsibility of maintaining it. TinyWork Apps has not tried to turn the experience into a complicated financial command center, and I see that restraint as both its appeal and its limitation.
The free entry point makes it easy to test with one account and one real purchase. Its Everyone age rating also makes the basic concept approachable for a broad audience, while the optional purchases mean I would review the upgrade choices carefully before spending. With over one hundred thousand installs, it is established enough to try, but the average score suggests that its manual style will not suit every user.
My advice is to install it only after deciding what success means: a trustworthy running balance for one account, updated as you spend. Start with the current balance, record a genuine transaction, include known commitments, and reconcile against the bank before expanding your setup. If that process feels reassuring rather than burdensome, this app can become a useful everyday checkbook companion. If you want your finances gathered and analyzed automatically, choose a banking or budgeting alternative instead.
Frequently Asked Questions
What is Checkbook - Account Tracker used for?
Checkbook - Account Tracker is designed to help you record and monitor personal financial activity in a simple checkbook-style interface. You can typically enter income, expenses, deposits, withdrawals, transfers, and other transactions, then review your balance and account history. It is useful for people who want a clearer picture of their spending without relying entirely on a bank’s mobile application.
Can I use Checkbook - Account Tracker for multiple accounts?
The app is intended for tracking more than one financial account, which can be helpful if you want to separate checking, savings, cash, credit, or other personal balances. Before downloading, check the current app description and settings because the number of accounts, account types, and available organization features may depend on the version or platform. It should be treated as a tracking tool rather than a replacement for official bank records.
Does Checkbook - Account Tracker connect directly to my bank?
Checkbook - Account Tracker generally focuses on manual transaction entry instead of automatically replacing your bank’s online banking service. This can give you more control over what is recorded, but it also means that balances and transaction histories depend on the information you enter. If your version offers importing, synchronization, or backup options, review the permissions and terms carefully before connecting any financial data.
Is Checkbook - Account Tracker safe for recording financial information?
The app may contain sensitive information such as account names, balances, transaction descriptions, and spending patterns, so you should review its privacy policy and requested permissions before using it. Avoid entering complete bank passwords, card PINs, or unnecessary personal details. Use a device passcode, keep the application updated, and confirm whether local protection, backup security, or biometric access is available on your device.
Is Checkbook - Account Tracker free to download and use?
Availability, pricing, advertisements, and premium features can vary between Android and iOS and may change with future updates. The basic download may be free while certain tools—such as additional accounts, reports, cloud backup, customization, or ad removal—could require a purchase or subscription. Check the store listing for the latest cost information and read any in-app purchase details before confirming a payment.